Dental practice startup costs cannot be reduced to one reliable national number. Rent, construction, equipment, permitting, staffing, technology, insurance, and the time needed to generate collections vary by location and practice model. A defensible budget therefore begins with written assumptions and current quotes, not an industry average copied into a loan request.
Use this checklist to build a zero-based estimate: identify everything the planned office requires, record when cash leaves the account, and show which costs remain uncertain.
Define the practice before pricing it
Write a one-page operating specification. Include the intended market, services, number of equipped operatories at opening, space reserved for later expansion, staffing by launch phase, days and hours open, major technology choices, and target opening window.
This specification prevents a common budgeting error: pricing a three-operatory office while planning the systems and payroll of a six-operatory practice. It also gives the architect, equipment supplier, technology vendors, insurer, and lender the same baseline.
Separate three labels:
- Required before opening: necessary for lawful, safe, functional operations.
- Required after a defined trigger: added when patient volume, staffing, or services reach a documented point.
- Optional: useful but not necessary for the launch model.
Coordinate the specification with the full dental practice business plan template. The budget explains cash needs; the business plan explains why the planned model can support them.
Price one-time startup uses of cash
Build a line-item schedule rather than broad categories. Every row should have a quantity, vendor or estimator, quote date, tax and delivery treatment, payment timing, confidence level, and contingency assumption.
Site, design, and construction
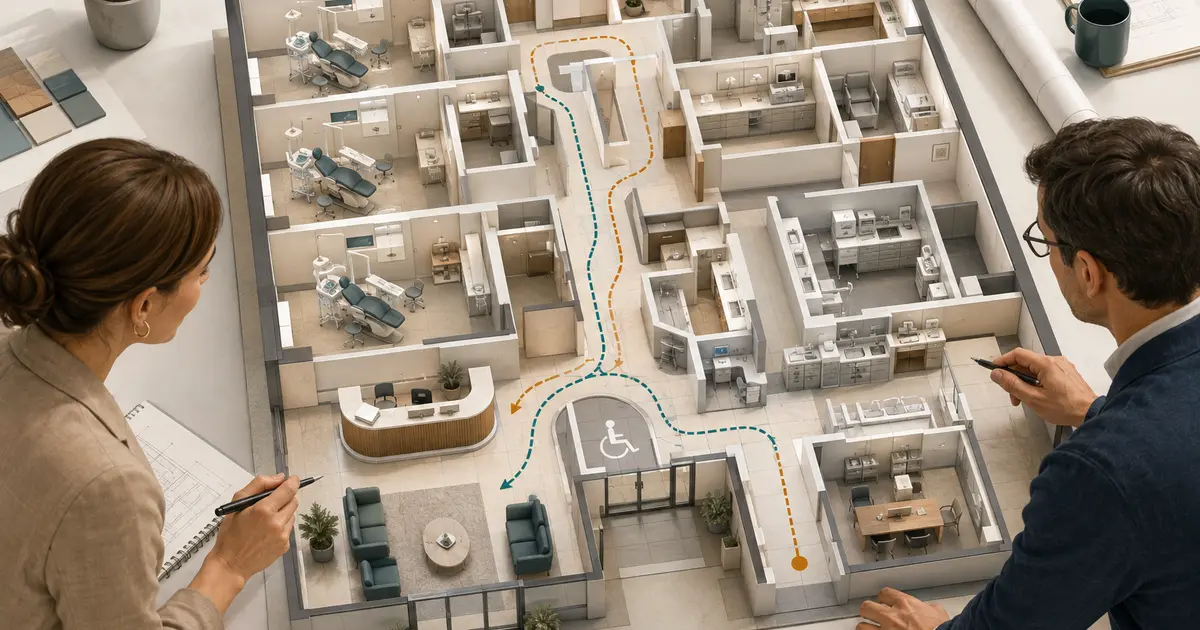
Include deposits, professional surveys, architectural and engineering work, legal lease review, permits, utility work, accessibility requirements, construction, dental plumbing, electrical capacity, ventilation, shielding where applicable, signage, security, furniture, and final inspections. Clarify which improvements the landlord pays for, which allowances are reimbursed later, and what happens if costs exceed the allowance.
Do not sign a lease because the base rent fits the model while the space itself has not been tested. A poor test fit can create expensive changes or leave no practical path for expansion.
Clinical equipment and initial supplies
Create an equipment list by room and function. Note new, refurbished, financed, leased, or transferred items separately. Include delivery, installation, training, warranties, service agreements, calibration, accessories, and consumables required to begin using each asset.
Initial inventory is not the same as normal monthly supply expense. Set opening quantities from expected use, lead time, storage capacity, and criticality. A par-level approach like the dental inventory management system can reduce both shortages and unnecessary launch purchases.
Technology and communications
Price networking, internet circuits, workstations, displays, phones, secure configuration, backups, software implementation, data migration, domain and website work, payment hardware, scanning, printers, and vendor support. Identify recurring subscriptions separately even when the first year is prepaid.
Include a pre-opening acceptance test for internet, voice quality, backups, user access, forms, payment workflows, and phone routing. A feature list does not prove the complete system works.
Professional, regulatory, and launch costs
Budget for qualified legal, accounting, tax, insurance, licensing, credentialing, compliance, and employment support appropriate to the state and ownership structure. Add recruiting, background checks where lawful, payroll setup, initial training time, branding, website production, local listings, and launch communications.
Fees and timing differ widely. Confirm requirements with the state dental board, state and local agencies, insurers, and advisers rather than relying on another office's checklist.
Model monthly cash needs before collections mature
Create a month-by-month operating model from lease signing through at least the first year of operations. Cash outflows often begin well before the first patient visit, while collections may lag services.
Include:
- rent, common-area charges, utilities, internet, and waste services;
- payroll, payroll taxes, benefits, recruiting, and training;
- clinical and office supplies;
- laboratory and external service costs;
- insurance premiums and professional services;
- software, phone, support, and security subscriptions;
- marketing and community outreach;
- loan payments and equipment commitments;
- refunds, merchant fees, and other payment costs;
- owner compensation assumptions stated separately.
Use at least three activity cases: slower than planned, base case, and stronger than planned. Do not improve the slower case merely by assuming every expense is variable. Rent, core payroll, insurance, and debt service continue even when appointment volume is below plan.
Link timing to a detailed dental office opening checklist so the budget reflects dependencies. A delayed permit or equipment delivery can extend rent and payroll before revenue begins.
Calculate working capital and contingency separately
Working capital covers the operating gap between paying obligations and collecting cash. Contingency covers uncertainty in the cost and timing of the project. They are not interchangeable.
Build a cash roll-forward for each month:
Opening cash + funding received + cash collections − capital payments − operating payments − debt payments = ending cash
Use cash collections, not production, in the calculation. Document payment lags, payer mix, patient payment timing, and the dates on which major deposits or construction draws are due.
Then list uncertainties in a contingency register. Examples include concealed site conditions, electrical upgrades, permitting changes, equipment substitutions, construction delays, additional training, and a slower patient ramp. Give each item a plausible range and mitigation owner. Do not hide every uncertainty inside one unexplained percentage.
Set a minimum cash threshold that triggers corrective action. Possible responses might include delaying an optional purchase, changing a hiring date, renegotiating a payment schedule, or securing additional committed funding before the threshold is reached. The response should be planned before cash becomes urgent.
Maintain a separate owner reserve decision outside the practice model. Personal living costs, taxes, student debt, and household obligations are not practice startup uses, but they can affect how much uncertainty the owner can carry. A financial adviser can help keep the two cash plans distinct.
Compare funding to the use and useful life
Match financing structure to the actual use of funds. Long-lived assets, leasehold improvements, working capital, and short-lived supplies do not necessarily belong in one term or product. Compare the amount funded, borrower contribution, fees, collateral, guarantees, draw rules, repayment start, variable-rate exposure, prepayment terms, and reporting obligations.
The U.S. Small Business Administration describes several loan programs, but eligibility and terms depend on the program, lender, borrower, and use of proceeds. A lender's preliminary conversation is not a commitment. Retain current written terms and have qualified legal, tax, and financial advisers review the complete transaction.
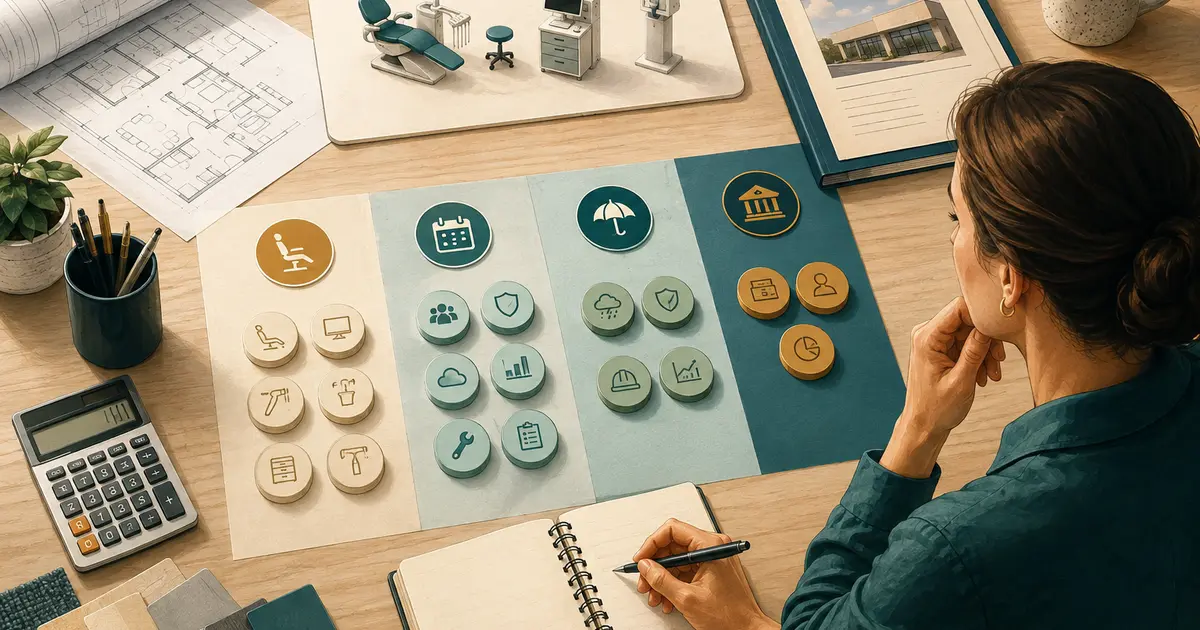
Build a sources-and-uses table:
| Use | Amount | Quote confidence | Payment date | Funding source | Unfunded gap |
|---|---|---|---|---|---|
| Lease and construction | |||||
| Equipment and installation | |||||
| Technology and implementation | |||||
| Professional and launch costs | |||||
| Working capital | |||||
| Contingency |
Do not count a landlord allowance as available cash until its reimbursement conditions and timing are understood. Do not count an unused credit line twice—once as construction funding and again as working capital.
Stress-test the budget before approval
Change one assumption at a time and observe the effect on the lowest cash point. Test a later opening, a construction overrun, lower initial collections, higher payroll, delayed credentialing, equipment replacement, and a higher variable interest rate where relevant.
Review the model with people who are accountable for its inputs. The architect should confirm the scope behind construction estimates. Vendors should confirm installation and training. The accountant should review timing, tax treatment, and model logic. The attorney should review contracts rather than the spreadsheet summary.
Keep tax treatment outside the operating assumptions until a qualified tax adviser confirms it. A deduction, depreciation method, or credit may change timing and after-tax economics, but it does not reduce the cash the project must pay when an invoice is due.
Before committing, reconcile every total to a quote or documented assumption, confirm that recurring charges were not omitted from the operating model, and lock a version for lender review. Record later changes as changes; do not overwrite the original estimate.
The goal is not to predict every dollar perfectly. It is to make the cost, timing, uncertainty, and funding gap visible early enough to act.