This guide shows how to audit a dental office phone bill: compare every recurring and usage charge with the current contract, number inventory, users, devices, locations, and features. Investigate anything that lacks an active business purpose or differs from the agreed rate. Then track the item until a credit, correction, or cancellation appears on a later bill.
Do not review only the total. A familiar total can hide an inactive number, former employee seat, unreturned device, expired promotion, new fee, or duplicate feature. A proper dental office phone bill audit creates a repeatable link between each charge and a real service the practice uses.
Gather the audit packet
Collect:
- the current detailed invoice;
- at least two prior invoices;
- the signed contract and amendments;
- the provider's current rate sheet or written order confirmations;
- a list of all phone numbers and their purposes;
- active users and extensions;
- desk phones, headsets, adapters, and leased equipment;
- locations and service addresses;
- recent adds, moves, changes, cancellations, and support tickets;
- credits or disputes still pending.
Use copies with only the information needed for review. Limit access to account numbers, call-detail records, payment information, and administrator credentials.
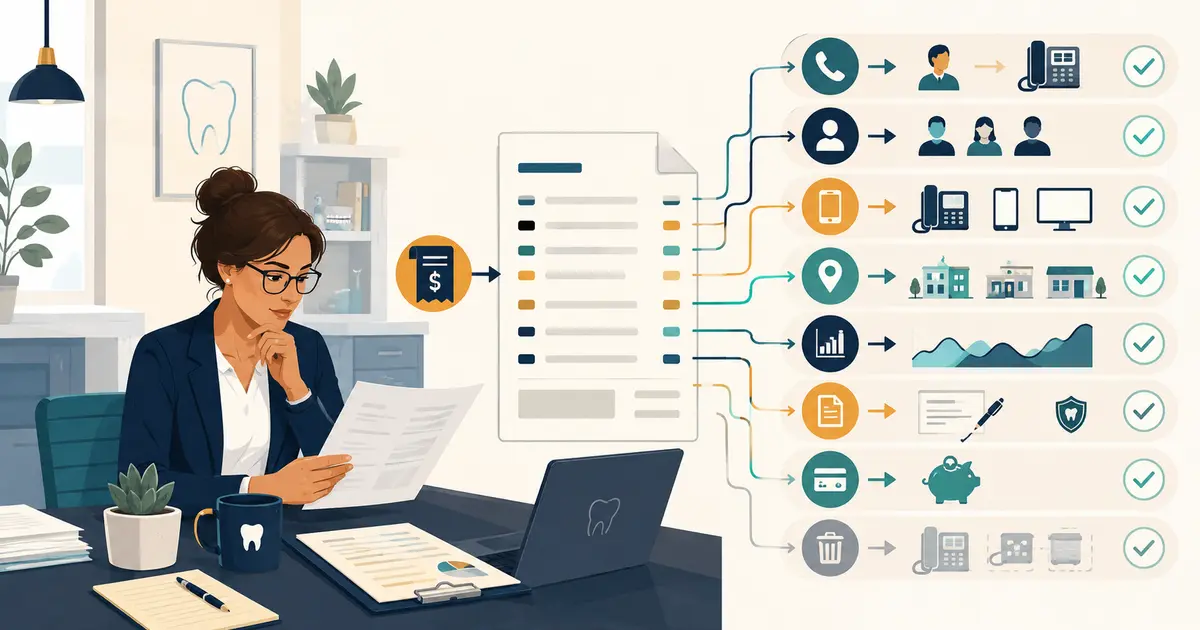
Build a line-item reconciliation sheet
Create one row for each billed item rather than one row per invoice.
| Invoice line | Quantity | Billed rate | Expected rate | Operational match | Variance | Action owner |
|---|---|---|---|---|---|---|
| Main voice plan | 1 | Contract/account | ||||
| User seats | Active-user list | |||||
| Local numbers | Number inventory | |||||
| Toll-free number | Public route | |||||
| Devices or leases | Hardware inventory | |||||
| Recording/storage | Approved feature owner | |||||
| Usage or overage | Call/usage report | |||||
| Taxes and fees | Provider explanation | |||||
| Credits/adjustments | Ticket or order |
Use this basic calculation:
Monthly variance = billed amount − expected amount
For an item that should have ended, calculate the review exposure without presenting it as recovered savings:
Potential annual exposure = unresolved monthly variance × 12
Treat the figure as a decision aid. It becomes verified savings only after the charge is removed or credited and remains absent on later invoices.
Step 1: reconcile quantities
Count first. Rates do not matter if the practice is paying for the wrong quantity.
Phone numbers
Match every billed number to the call-tracking number inventory or the practice's master number list. Confirm whether it is:
- the main public number;
- a location or department number;
- toll-free;
- fax;
- a marketing tracking number;
- a temporary porting or forwarding number;
- an old number that should be retired;
- unknown.
Call or otherwise test unknown numbers according to the practice's approved process before canceling them. A number that appears unused may still be printed on old referral materials or tied to a system.
Users and extensions
Compare billed seats with current staff and shared work areas. Look for:
- former employees;
- duplicate accounts;
- seasonal or temporary access that never ended;
- users assigned to the wrong pricing tier;
- shared phones billed as individual premium users;
- add-on licenses that no one recognizes.
Devices
Reconcile serial numbers or device identifiers when available. Determine whether each item is owned, leased, financed, rented, or included. A phone hardware inventory helps distinguish missing equipment from a billing error.
Step 2: reconcile rates and terms
For each line, find the document that establishes the expected rate. Check:
- base monthly rate;
- quantity tiers;
- promotional period and expiration;
- annual increase;
- support level;
- contract minimum;
- device payment;
- installation or one-time charge;
- usage rate;
- toll-free rate;
- storage or recording rate;
- taxes, surcharges, and regulatory fees;
- credits promised in an order or ticket.
Do not label a charge “unauthorized” merely because the reviewer does not recognize it. Find the provider description and agreement first. The FCC's telephone-bill guidance recommends understanding bill sections and charges and reviewing for services that were not ordered.
Step 3: review usage without exposing call details
Usage charges may come from toll-free minutes, international calls, directory assistance, premium services, overage, fax, messaging, or data. Compare the billed unit, count, period, and rate with the provider report.
Investigate:
- a sudden category that never appeared before;
- usage outside expected locations or hours;
- a rate different from the contract;
- calls attached to a number the practice does not recognize;
- overlapping plans that both charge for the same function;
- continued usage after a service was changed.
Use aggregated reports when possible. Do not copy patient phone numbers or call records into a broadly shared finance sheet.
Step 4: inspect taxes, fees, credits, and adjustments
Charges may be provider-imposed, government-required, usage-based, or tied to a particular service. Ask the provider to explain unfamiliar lines in writing. The reviewer does not need to become a telecommunications tax expert, but the practice should understand whether a line is:
- required and calculated correctly;
- allowed by the agreement;
- duplicated;
- attached to the wrong quantity;
- newly introduced;
- credited elsewhere;
- still under dispute.
Track credits as carefully as charges. A promised credit may appear once, be applied to a different account, or never arrive.
Common phone billing leaks
Look for these patterns:
- A disconnected employee still has a paid seat.
- A tracking number remained after a campaign ended.
- A device lease continues after equipment was returned.
- A temporary forwarding number became permanent.
- A free feature converted to a paid add-on.
- A support tier was upgraded during an incident and never reduced.
- A cancelled service remains on the next invoice.
- An annual increase does not match the agreement.
- A multi-location account bills the same feature twice.
- A credit appears in correspondence but not on the invoice.
- Old and new providers overlap longer than planned.
- A minimum commitment prevents the apparent cancellation from reducing the bill.
Some items are operational waste rather than provider errors. Assign each finding as explain, keep, change, cancel, dispute, or monitor.
Dispute template
Keep the request factual:
Subject: Billing review for account [last four digits or approved identifier]
>
We are requesting review of the following invoice item:
>
Invoice date and number: [details] Line description: [exact wording] Billed quantity/rate: [details] Expected quantity/rate: [details and supporting document] Requested action: [explanation, correction, cancellation, or credit] Effective date requested: [date] Practice contact authorized to discuss the account: [name/role]
>
Please confirm the ticket number, effective date, and how the result will appear on the invoice.
Attach only necessary records. Never email passwords, security answers, or full payment credentials.
Verify the result
A submitted request is not a completed audit finding. Record:
- provider ticket or case number;
- representative and contact date;
- provider response;
- effective date;
- credit amount, if any;
- cancellation or configuration confirmation;
- invoice on which the change should appear;
- reviewer and closure date.
Check the next invoice and, for recurring items, at least one later invoice. If a cancellation reduces one line but creates an unexpected fee elsewhere, keep the finding open.
Set a sensible audit cadence
Review monthly for the first few bills after a new contract, location, port, or major change. Stable accounts may need a detailed review quarterly, with a lighter monthly variance check. Also trigger an audit after:
- a staff or location change;
- new numbers or devices;
- a provider migration;
- a major incident;
- contract renewal;
- an unexpected total increase;
- cancellation of a service.
Coordinate the findings with the dental answering service budget or broader communications budget, but keep invoice reconciliation distinct from deciding which solution offers the best value.
One-page audit summary
Report:
- invoice period and accounts reviewed;
- total billed and expected;
- explained variance;
- unresolved variance;
- items to keep, change, cancel, or dispute;
- verified credits;
- owner and due date for every open item;
- next invoice to review.
This gives the practice owner a decision-ready view while preserving line-level evidence in the controlled worksheet.